Before you start
- Method selection follows the business model and available evidence.
- A multiple cannot be assessed separately from the earnings definition it is applied to.
- Risk may be reflected in the earnings, multiple, discount rate or specific adjustments, but should not be counted twice.
- A reasoned range is often more informative than false precision.
Match the method to the question
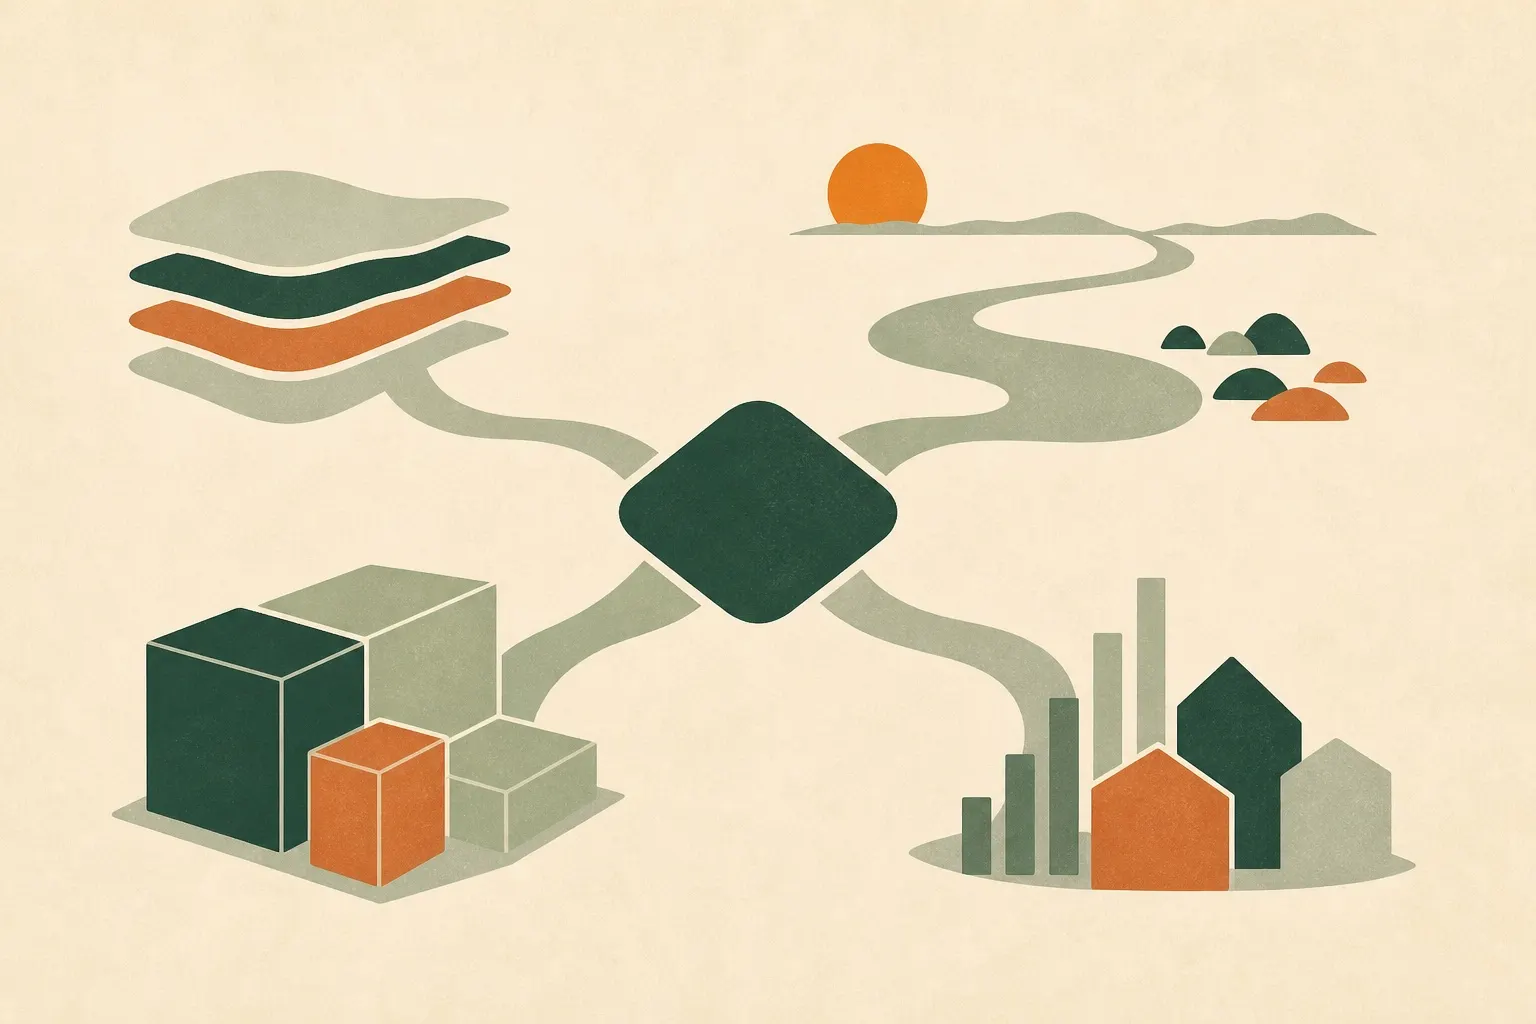
This is a starting guide, not a rule that assigns a method by industry. A valuer may use one primary method and another as a cross-check.
| Approach | Useful starting situation | Main point to test |
|---|---|---|
| Capitalised earnings | Established operations with reasonably stable earnings | Whether the earnings and selected multiple use the same basis |
| Discounted cash flow | A credible forecast of materially changing cash flows | Whether forecast growth, reinvestment and risk assumptions hold together |
| Asset-based | Value is concentrated in identifiable assets, or continued trading is in question | Whether the assets and liabilities are measured on the right basis |
| Market comparison | Enough relevant, understood transaction evidence is available | Whether price, earnings and deal terms are actually comparable |
Capitalisation of maintainable earnings
This approach estimates a maintainable level of earnings and applies a capitalisation multiple that reflects growth, risk, transferability and market evidence. It is commonly considered for established SMEs with a reasonably stable earnings history.
The earnings measure might be based on EBITDA, EBIT or another defined basis depending on the business and transaction context. The multiple only makes sense when the earnings definition, working capital assumptions and treatment of debt and surplus assets are also clear.
Discounted cash flow
A discounted cash flow analysis estimates future cash flows and discounts them to present value using a rate that reflects risk and the time value of money. It can be useful when future performance is expected to differ materially from recent history or cash flows can be forecast with a reasonable basis.
The result can be highly sensitive to revenue growth, margins, capital expenditure, working capital, terminal value and discount rate. A detailed spreadsheet does not remove uncertainty, so assumptions and sensitivity analysis matter.
A profit multiple does not tell you the cash available
Consider a fictional business with $300,000 EBITDA. If it needs $70,000 of annual equipment replacement and another $40,000 tied up in inventory and receivables as it grows, those two demands leave $190,000 before tax, financing and other cash movements. EBITDA has not changed, but the cash available has.
That difference matters when comparing an equipment-heavy business with a service firm. Ignoring replacement expenditure can make a seemingly cheap earnings multiple less attractive. A cash-flow method makes these assumptions explicit; an earnings method still needs to account for them in the analysis.
Asset-based approaches
An asset approach considers the value of assets less liabilities, often after adjustments to reflect an appropriate value basis. It may be relevant for asset-intensive businesses, holding entities, businesses with weak earnings or circumstances where orderly realisation is more relevant than continued trading.
Book value is not automatically market value. Equipment condition, property, inventory recoverability, intangible assets, liabilities and costs of realisation may require separate consideration.
Market and transaction evidence
Comparable transactions can help inform a multiple or test a conclusion. The challenge is determining whether the businesses, earnings definitions, transaction terms, dates and risk profiles are comparable.
Private SME transaction data can be incomplete. Headline sale prices may include stock, working capital, property, earn-outs or vendor finance, while the published earnings figure may use a different normalisation basis. Evidence should be adjusted and weighted with care.
Enterprise value and equity value
A valuation may first determine the value of business operations, often described as enterprise value, and then consider debt, surplus cash and other non-operating assets or liabilities to arrive at equity value. The exact bridge depends on the valuation basis and transaction assumptions.
Confusion between enterprise and equity value is a common reason two parties appear to disagree even when they have applied similar earnings multiples.
Cross-checking the conclusion
Where the evidence permits, comparing the primary method with another approach can expose inconsistent assumptions or an implausible result. The final report should explain why a method was selected, how inputs were derived and where judgement or limitations remain.
Sources and further reading
The examples in this guide are illustrative. These references explain the underlying principles and offer further practical guidance.
- Australian Taxation Office: Market valuation for tax purposes
Describes valuation approaches, method selection, evidence and cross-checks. Its tax-specific requirements are separate from an ordinary commercial engagement.
- International Valuation Standards Council: International Valuation Standards
The international valuation framework includes IVS 200 for businesses and business interests, alongside general standards on approaches, inputs and reporting.
General information for Australian business owners. A valuation depends on the business, valuation date, purpose and evidence. Seek advice on your circumstances before a transaction or ownership change.
Apply this to your business.
Tell us the decision you need to make. We can help you choose the right level of valuation work.
Discuss a valuation